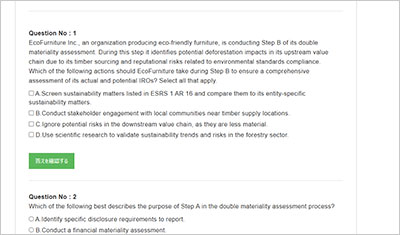
サンプル問題 1: Which of the following correctly fills the gaps in the paragraph below? The first set of the ESRS consist of several standards: The first group includes __________ General requirements and __________ General disclosures. These standards apply regardless of the specific sustainability topic being reported. The next group includes ten __________ that cover various topics across the three dimensions of sustainable development. For example, ESRS E1 focuses on the environmental dimension, particularly climate change. Finally, the last group includes the __________ which are currently under development.
Explanation: The ESRS (European Sustainability Reporting Standards) framework consists of three primary categories of standards: ESRS 1 (General Requirements): ESRS 1 sets out the fundamental principles and requirements for sustainability reporting. It provides an overview of the structure and drafting conventions of the ESRS framework, defining the categories of ESRS standards: cross-cutting, topical, and sector-specific. It also establishes the double materiality principle as the basis for sustainability disclosures. ESRS 2 (General Disclosures): ESRS 2 outlines the core disclosure requirements applicable to all sustainability topics, ensuring comparability and completeness. It includes general governance, strategy, impact, risk, and opportunity management disclosures applicable to all sustainability topics. These disclosure requirements apply to all undertakings regardless of the specific sustainability topics being reported. Topical Standards: The ESRS framework includes ten topical standards covering the three key dimensions of sustainability: Environmental (E): ESRS E1 (Climate Change), ESRS E2 (Pollution), ESRS E3 (Water & Marine Resources), ESRS E4 (Biodiversity & Ecosystems), and ESRS E5 (Resource Use & Circular Economy). Social (S): ESRS S1 (Own Workforce), ESRS S2 (Workers in the Value Chain), ESRS S3 (Affected Communities), and ESRS S4 (Consumers & End-users). Governance (G): ESRS G1 (Business Conduct). These standards provide specific requirements on sustainability matters, complementing the general disclosure requirements in ESRS 2. Sector-Specific Standards: Sector-specific ESRS are currently under development. These will address sustainability matters specific to different industries, ensuring that sectoral nuances are properly considered. They aim to fill gaps not sufficiently covered by the topical standards by defining industry-specific impacts, risks, and opportunities. Why is C. ESRS 1; ESRS 2; topical standards; sector-specific standards the correct answer? ESRS 1 (General Requirements) comes first, setting the foundation. ESRS 2 (General Disclosures) follows, providing cross-cutting disclosure requirements. Topical standards are next, covering specific sustainability topics. Sector-specific standards are the final category, though they are still in development. Thus, the correct order aligns with the official structure of the ESRS framework as mandated in Commission Delegated Regulation (EU) 2023/2772. Official Commission Delegated Regulation (EU) 2023/2772, various EFRAG guidance documents, and CSRD-related references: Commission Delegated Regulation (EU) 2023/2772, Annex I: Structure of the ESRS framework. EFRAG Compilation of Explanations (January - November 2024): Explanation of ESRS categories. EFRAG Mapping of Sustainability Matters to Topical Disclosures (Q&A ID 177): Confirmation of ESRS 1, ESRS 2, and the ten topical standards
サンプル問題 2: What are the two categories of stakeholders identified in the ESRS?
A: Affected stakeholders and users of sustainability statements.
B: Primary and secondary stakeholders.
C: Internal and external stakeholders.
正解:A
Explanation: The European Sustainability Reporting Standards (ESRS) categorize stakeholders into two main groups: Affected Stakeholders: These are individuals or groups whose interests are affected (positively or negatively) by the undertaking’s activities and business relationships across its value chain. Examples include workers (own workforce and those in the value chain), affected communities, consumers, and end-users. The identification of affected stakeholders plays a crucial role in an organization’s sustainability due diligence and materiality assessment processes. Users of Sustainability Statements: These are primary users of sustainability disclosures, including investors, lenders, and other creditors. Additional users include business partners, trade unions, civil society organizations, non-governmental organizations (NGOs), governments, analysts, and academics. The ESRS framework emphasizes the importance of engagement with affected stakeholders as part of an undertaking’s due diligence and materiality assessment process, ensuring that material impacts, risks, and opportunities are adequately identified and reported. Official Reference: Commission Delegated Regulation (EU) 2023/2772, ESRS 1, Section 3.1 - Defines the two main groups of stakeholders. ESRS 2 SBM-2 (Interests and Views of Stakeholders) - Covers how affected stakeholders' views inform an undertaking’s strategy. EFRAG Guidance on Stakeholder Engagement and Double Materiality - Reinforces the role of affected stakeholders in sustainability assessments.
サンプル問題 3: Which of the following correctly fills the gaps in the paragraph below? Under the ESRS, engagement with affected stakeholders is a core element of __________. The outcome of the due diligence process informs __________. The ESRS encourage further engagement with stakeholders to collect their input and feedback on the organization's conclusions regarding __________.
A: the materiality assessment; the material impacts, risks, and opportunities; due diligence
B: the materiality assessment; due diligence; the material impacts, risks, and opportunities
C: due diligence; the materiality assessment; the material impacts, risks, and opportunities
D: the material impacts, risks, and opportunities; due diligence; the materiality assessment
正解:C
Explanation: Under the ESRS, engagement with affected stakeholders is a core element of due diligence. The outcome of the due diligence process informs the materiality assessment. The ESRS encourage further engagement with stakeholders to collect their input and feedback on the organization's conclusions regarding the material impacts, risks, and opportunities. This sequence is supported by the official text of Commission Delegated Regulation (EU) 2023/2772 and various ESRS-related documents. The standard emphasizes due diligence as a starting point for the materiality assessment process. The assessment then determines the organization's material impacts, risks, and opportunities, which is crucial for effective stakeholder engagement. Due Diligence: The ESRS process starts with due diligence, as outlined in the Commission Delegated Regulation (EU) 2023/2772, to identify relevant sustainability matters and affected stakeholders. Materiality Assessment: The findings from the due diligence process are then used to inform the materiality assessment, as discussed in EFRAG's guidance documents. Material Impacts, Risks, and Opportunities: Finally, the organization engages with stakeholders to review and refine its conclusions about material impacts, risks, and opportunities, as per the ESRS requirements. Reference: Commission Delegated Regulation (EU) 2023/2772 of 31 July 2023 supplementing Directive 2013/34/EU EFRAG Guidance on Materiality Assessment in ESRS ESRS Due Diligence Framework, as outlined in Compilation Explanations and Mapping Sustainability Matters with Disclosure Requirements
GOWUKAKUのESRS-Professional問題集は、GRI ESRS Professional Certification Exam認定試験の準備に向けた復習用問題集です。ESRS-Professional問題集を使用して出題形式を確認し、知識の定着度を確認しながら復習を進めることができます。